VAT in Slovakia
Learn what VAT registration in Slovakia involves and how to obtain a Slovak VAT number. Our lawyers can assist you with the whole registration procedure.
Below, we invite you to discover what it entails to obtain a VAT number in Slovakia, as well as the services provided by our lawyers in association with this tax.
| Quick Facts | |
|---|---|
| VAT registration services available (YES/NO) | Yes |
Standard rate | 23% |
Lower rates | 19% on certain foodstuffs and electricity; 5% on basic foods, medicines, books and accommodation, 0% on international passenger transport |
| VAT registration requirements | EUR 50,000 annual turnover (immediate registration above EUR 62,500) |
| Registration time frame (approx.) | Approx. 3 weeks |
| VAT for real estate transactions | 23% on new buildings (within 5 years of first approval or use); later sales of buildings and sales of non-building land are generally exempt |
| Exemptions available (YES/NO) | Yes, supply of goods in the EU, international passenger transport, export of goods outside the EU, financial and insurance services, supply of real estate |
| Filing period | Monthly or quarterly filings are permitted |
| VAT returns support (YES/NO) | Yes |
| VAT refund availability (YES/NO) | Yes for Slovak residents buying goods from other EU member states |
| Local tax agent required (YES/NO) | Not mandatory, but this service is available on demand |
| Availability of other reduced rates (if any) | Yes, a new 5% rate applicable to certain foods, accommodation services, restaurant services, and essential hygiene products is now available. |
Who needs VAT registration? | Both companies and natural persons must register for VAT if they carry out VAT-taxable activities. |
VAT number format | Country code SK+10 digit sequence. |
| Documents for VAT registration in Slovakia | – application form, – details about the registrant (Certificate of Incorporation in the case of companies), – details of the liaison officer. |
| Reporting currency | Reporting must be done in Euro. |
| VAT registration requirements for distance sale of goods | EUR 10,000 for intra-Community sales. |
| VAT records maintenance requirements | At least 10 years. |
| Invoice content | – name and address of the seller/service provider, – VAT registration code, – price with and without the VAT, – the applicable VAT rate, – the product sold/service provided, – total amount due. |
| Invoice issue time limit | A maximum of 15 days from the date of the supply of goods or services. |
| Penalties for late VAT returns | A fine from EUR 100 to EUR 30,000. |
| VAT de-registration situations | – company dissolution, – business no longer meets the turnover required for VAT registration. |
| Registration requirements for foreign companies (YES/NO) | Yes, foreign companies must also register for VAT in Slovakia. |
| Authority in charge of VAT collection in Slovakia | Financial Administration of the Slovak Republic (tax offices). |
| Possibility to apply for EORI numbers (YES/NO) | Yes, such a number is issued only after VAT registration. |
| Penalties for late VAT payments in Slovakia (if any) | 4 times the late interest late payment rate as imposed by the European Central Bank, or a penalty of 15% of the VAT amount due. |
Who is required to register for VAT in Slovakia?
The following taxpayers are required to apply for VAT registration in Slovakia:
- taxable persons and companies that have their residence, respectively, management places on the territory of the country and have registered a turnover exceeding 50,000 euros in a calendar year;
- taxable persons and companies that have not reached the registration threshold but want to register voluntarily;
- taxpayers registered in other countries who conduct business activities liable to VAT in Slovakia;
- foreign entities operating through branch offices that complete VAT-payable supply of goods and services;
- groups of companies are also allowed to register for VAT in Slovakia under certain circumstances.
What documents are required to register a foreign company for VAT in Slovakia?
The necessary forms that must be filled out and sent to the Slovakian tax office with the supporting evidence are listed below by our Slovak lawyers:
- if required, a VAT certificate demonstrating that the company is registered for VAT elsewhere in the EU;
- a certified translation into Slovak of an original extract from the company’s national trade registration (notarized or court-stamped);
- passport of the company’s representative.
Before beginning any taxable activity, non-resident enterprises must submit the registration form and supporting materials to the Slovakian tax authorities in Bratislava.
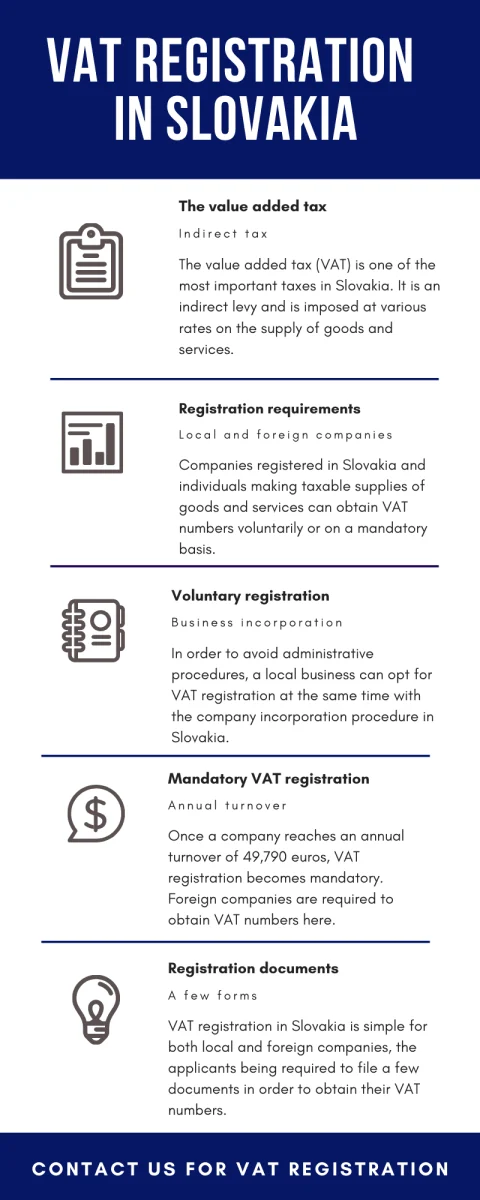
We invite you to read about the VAT registration procedure in Slovakia in the scheme below:
What are the VAT registration documents for local businesses in Slovakia?
Local companies or sole proprietorships are required to submit an application form alongside information about their status as taxpayers in Slovakia. In the case of entities applying for voluntary VAT registration, these are required to file an estimate of the expected turnover.
Companies and other entities are required to register for VAT with the tax offices in the Slovak cities they operate in. These fall under the administration of the Ministry for Finance in Slovakia.
Are there any exceptions from VAT registration in Slovakia?
Yes, the following:
- you sell goods in Slovakia to a Slovak entity;
- you rent a property located in Slovakia to a domestic business.
Are there any VAT registration thresholds in Slovakia?
Yes, for local companies, the mandatory registration threshold is EUR 50,000 within a calendar year, or immediately if the turnover of the company is EUR 62,500.
Does the VAT registration threshold apply to foreign companies too?
No, foreign enterprises must register for VAT upon commencing commercial activities in Slovakia, otherwise facing non-compliance penalties.
Are there any particular VAT registration requirements for e-commerce companies in Slovakia?
Yes, for distance selling operations, the EU registration threshold applies, which is EUR 10,000.
Is it necessary for a foreign company to appoint a fiscal representative for VAT purposes in Slovakia?
No, Slovak VAT law does not require this (a tax representative is optional, e.g. for imports), including in the case of non-resident businesses (companies that do not have a physical presence in Slovakia). For foreign enterprises operating through branches or subsidiaries in Slovakia, this requirement does not apply.
Is there any special aspect to consider when registering for VAT in Slovakia?
Yes, the applicant must inform the Slovak Tax Office about the bank account(s) that will be used in the transactions linked to the VAT-taxable operations, as presented on the website of the Financial Administration of the Slovak Republic.
How is the registration procedure completed, and how long does it take?
The documents can be filed online, in person, or sent by post; however, the first option is selected by most applicants nowadays. The tax office issues the VAT registration decision within 21 days of receiving the application.
We also invite you to watch a video:
What are the 2026 VAT rates in Slovakia?
Here they are:
- 23% standard rate, which applies to most goods and services in Slovakia;
- 19% reduced rate, which applies to certain foodstuffs, electricity supply and non-alcoholic drinks served in restaurants;
- 5% reduced rate, which applies to basic foods, medicines, books, accommodation and restaurant meals (residential rentals are VAT-exempt).
Are there any goods/services exempt from VAT in Slovakia?
Yes, among them are:
- supply of goods to another EU country;
- international passenger transport services;
- the export of goods outside the EU.
- financial and insurance services;
- supply and rental of real estate.
IMPORTANT! Please note that documents issued in your home country must first be translated into Slovak before being submitted to the Tax Office for VAT registration.
You can also rely on us for support in immigration to Slovakia.
Persons who are interested in receiving more details on Slovakia’s VAT registration procedure can contact our Slovak law firm for legal assistance on this matter.
Juraj Kornhauser, Attorney at Law · 2 October 2026